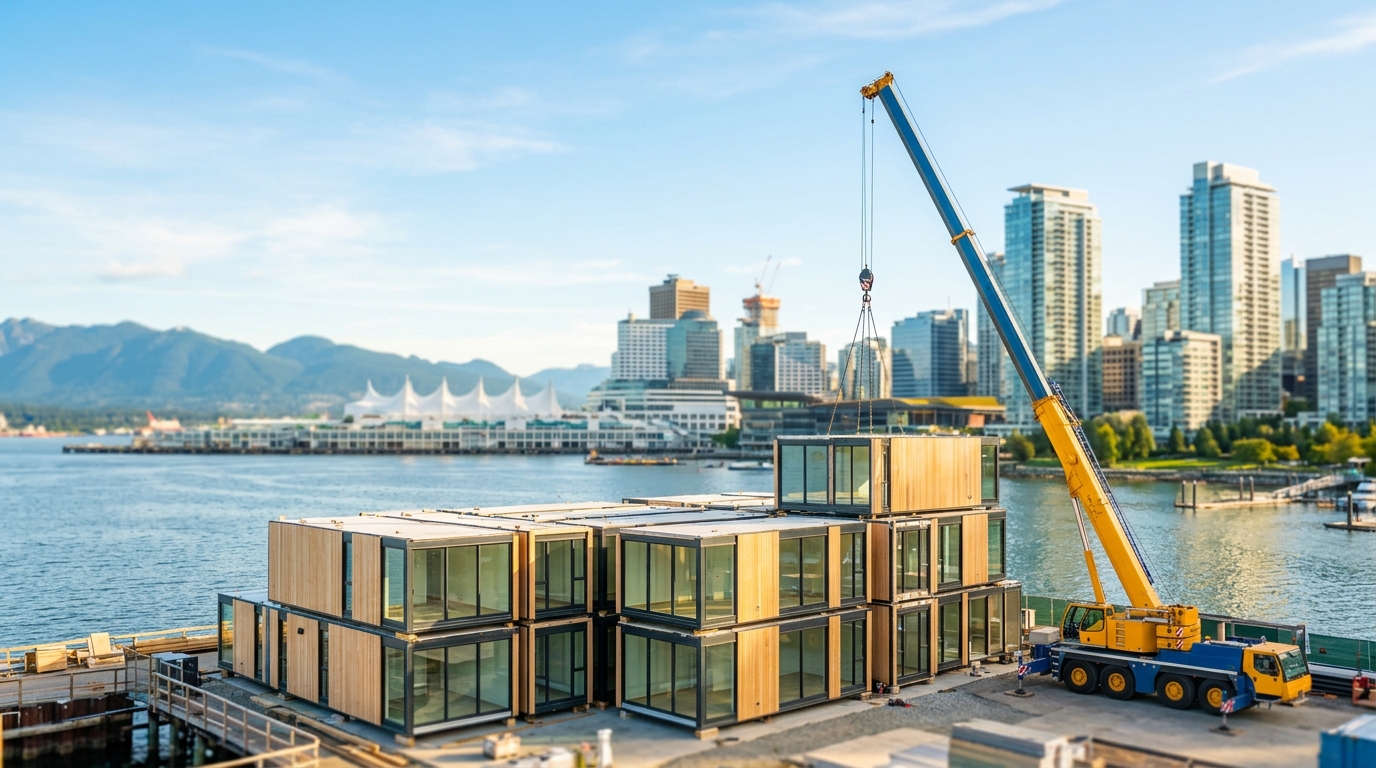
In a Fraser Valley factory, the math is simple, but the execution is not. A modular housing unit—complete with tiled bathrooms, pre-run wiring, and cabinetry—rolls off an assembly line in a fraction of the time required for on-site framing. These units offer superior insulation, controlled-environment inspections, and lower costs per square foot compared to stick-built equivalents. While order books are full, the bottleneck lies in the next phase: securing the workforce to build the next unit, finding the floor space to scale production, and managing the crane logistics required for site installation.
This operational friction defines BC's modular construction sector in April 2026. For investors and developers with operational discipline, however, these challenges represent a significant opportunity.
Federal capital, provincial advantage
Ottawa's Housing Accelerator Fund, administered by the Canada Mortgage and Housing Corporation (CMHC), now represents a $4.4 billion investment to boost housing supply nationwide. A meaningful share of this capital targets factory-built and modular construction—technologies CMHC identifies as credible pathways to increasing supply without proportionally scaling on-site labour costs. BC manufacturers, concentrated in the Lower Mainland and the Okanagan, are positioned to capture a significant portion of this federal flow.
The province's advantage is structural. BC boasts an established cluster of modular manufacturers, a regulatory environment that increasingly accommodates factory-built housing in municipal zoning, and proximity to Pacific port networks for component imports. CMHC's factory-built housing research consistently shows BC punching above its population weight in modular starts as a share of national totals—a position federal procurement is set to reinforce.
Municipal housing delivery targets are accelerating the timeline. Vancouver's housing targets and Surrey's delivery commitments under federal Housing Accelerator agreements create a public procurement pipeline that favours manufacturers capable of demonstrating volume capacity.
The three constraints
Industry observers identify three interlocking operational constraints that define the sector's scaling ceiling.
The first is skilled assembly labour. Modular construction requires a specific blend of trades—framers, electricians, plumbers, and finish carpenters—working in a factory environment. While this offers a more stable environment than outdoor construction, it competes directly with the labour pool required for LNG Canada, infrastructure megaprojects, and conventional residential construction. BCIT enrolment data and union reporting from the building trades highlight a persistent gap between training output and industry demand—a gap modular manufacturers feel acutely, as their production model depends on consistent, specialized crews.
The second constraint is factory floor space. While the Lower Mainland's industrial real estate market has softened modestly, large-format manufacturing space remains scarce and expensive. Expanding production capacity requires either acquiring or leasing additional space at costs that compress margins, or pushing existing facilities to utilization rates that leave no buffer for quality control or maintenance.
The third constraint is crane logistics. A modular unit delivered to an infill site must be craned into position, often in dense urban blocks with limited staging areas, overhead utilities, and narrow access windows. Crane availability in Metro Vancouver is tight, scheduling is complex, and errors are costly. For a manufacturer, crane logistics can become the single point of failure that disrupts an efficient factory process.
The margin opportunity
For investors, the opportunity lies in the efficiency gap. Modular construction can deliver a meaningful per-unit cost advantage over conventional stick-built methods, a differential that widens as labour costs rise and on-site productivity stagnates. Currently, that advantage is partially absorbed by operational inefficiencies: overtime to compensate for labour gaps, underutilized floor space, and crane scheduling premiums.
The operator who systematically solves these constraints—through workforce development partnerships with institutions like BCIT, strategic industrial real estate acquisition, and dedicated crane contracting arrangements—builds more than just housing; they build a competitive moat. In a public procurement environment where buyers increasingly prioritize demonstrated delivery capacity over lowest-bid pricing, that moat translates directly to contract flow and margin protection.
The bottom line
Federal Housing Accelerator capital is not the constraint facing BC's modular sector; it is the catalyst that makes solving operational bottlenecks urgent and lucrative. Labour pipelines, factory footprints, and crane logistics are solvable problems for operators with capital, patience, and the right partnerships. Manufacturers and investors who treat this moment as a systems-building exercise rather than a volume sprint will be best positioned to win contracts as public procurement hits full stride through 2026 and 2027.
Watch for capital expenditure announcements from BC's established modular manufacturers, union partnership agreements targeting factory-specific trades training, and industrial strata or lease transactions in the Fraser Valley and Okanagan that signal a manufacturer is betting on its own expansion. These are the indicators that a firm has decided the bottleneck is worth breaking.



