The spreadsheet that made sense in 2022 no longer closes. For thousands of Metro Vancouver condo investors who built their cash-flow models around short-term rental (STR) yields, BC's Short-Term Rental Accommodations Act has decisively changed the arithmetic. Now, more than a year into the May 1, 2024, implementation of the principal residence requirement, the secondary effects are measurable: listing volumes are shifting in key submarkets, strata councils are navigating bylaw disputes, and long-term rental operators are evaluating units that were previously priced out of reach.
The provincial legislation restricts most short-term rentals to a host's principal residence. For investor-owned condos—units purchased specifically to operate as de facto hotel rooms—this restriction effectively terminates that business model. The province's intent was to return these units to the long-term housing supply. Whether that transition produces a wave of distressed sales or a shift toward long-term stability depends on the submarket.
Three Submarkets, Three Different Shocks
The impact is not uniform. Downtown Vancouver and North Vancouver’s waterfront segment present distinct pictures of investor repositioning, while resort municipalities like Whistler operate under different regulatory frameworks.
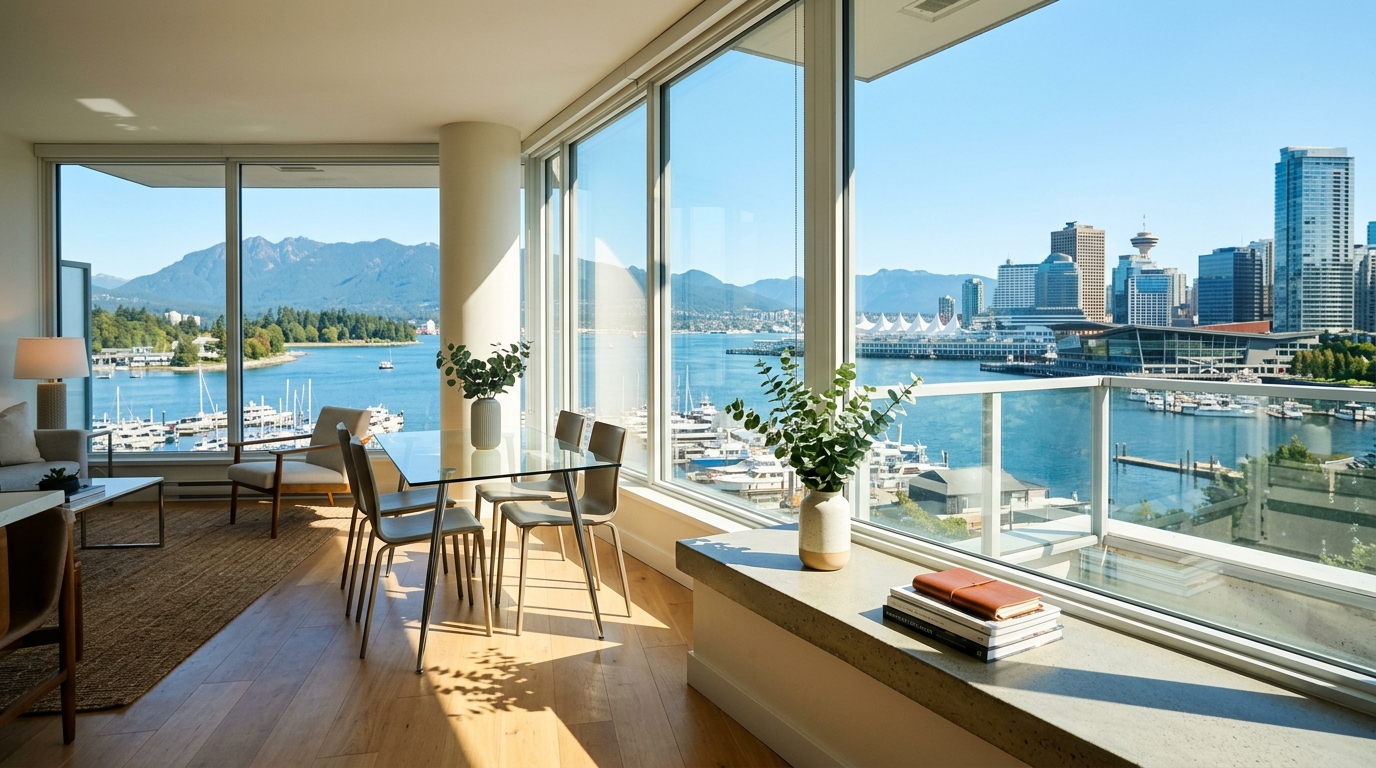
Downtown Vancouver is where the volume shift is most visible. The concentration of investor-owned condos in buildings explicitly marketed as STR-friendly—particularly in the Coal Harbour, Yaletown, and False Creek corridors—means a substantial pool of units is re-entering the conventional market. Days-on-market metrics suggest that price expectations set during the STR era are colliding with the reality of long-term rental income. A unit that generated $6,000 to $8,000 per month as a short-term rental cannot easily be repositioned at $3,200; the gap represents a fundamental recalculation of asset value.
Whistler remains a unique case. As a resort municipality, it is exempt from the provincial principal residence requirement. Investors in this corridor continue to operate under local municipal bylaws rather than the provincial Act. Consequently, the market dynamics here are driven by local zoning and licensing policies rather than the province-wide shift affecting urban centres.
North Vancouver's waterfront condo segment highlights the challenges of strata governance. In buildings with permissive rental bylaws, the impact is less about total volume and more about internal friction. Councils are navigating contested bylaw amendments as owners push back against restrictions. Dispute filings tracked by the Civil Resolution Tribunal (CRT) reflect this tension, as STR-related bylaw conflicts have become a frequent category of governance disputes.
The Conversion Calculation
For investors choosing to stay, the pivot to long-term rental is complex. CMHC's rental market data shows that Metro Vancouver's vacancy rate remains tight even as condo rental supply grows. This gives converting investors some pricing power, though it rarely offsets the total yield compression from exiting the STR model.
Successful conversions often involve one- and two-bedroom layouts in transit-proximate locations with modern amenities. Buildings near SkyTrain stations in the Broadway corridor or near the Lonsdale Quay SeaBus terminal are absorbing converted units more effectively than car-dependent towers.
The Bottom Line
BC's short-term rental crackdown is a market repricing. The investors most exposed are those who paid a premium for STR potential and are now selling into a market that has removed that premium from valuations. The investors best positioned are those who bought based on long-term fundamentals. For observers, the next 12 months will determine whether this repricing produces genuine entry opportunities or a prolonged period of strata conflict. Watch the CMHC vacancy trends and the CRT bylaw dispute pipeline; the friction is where the story is.



