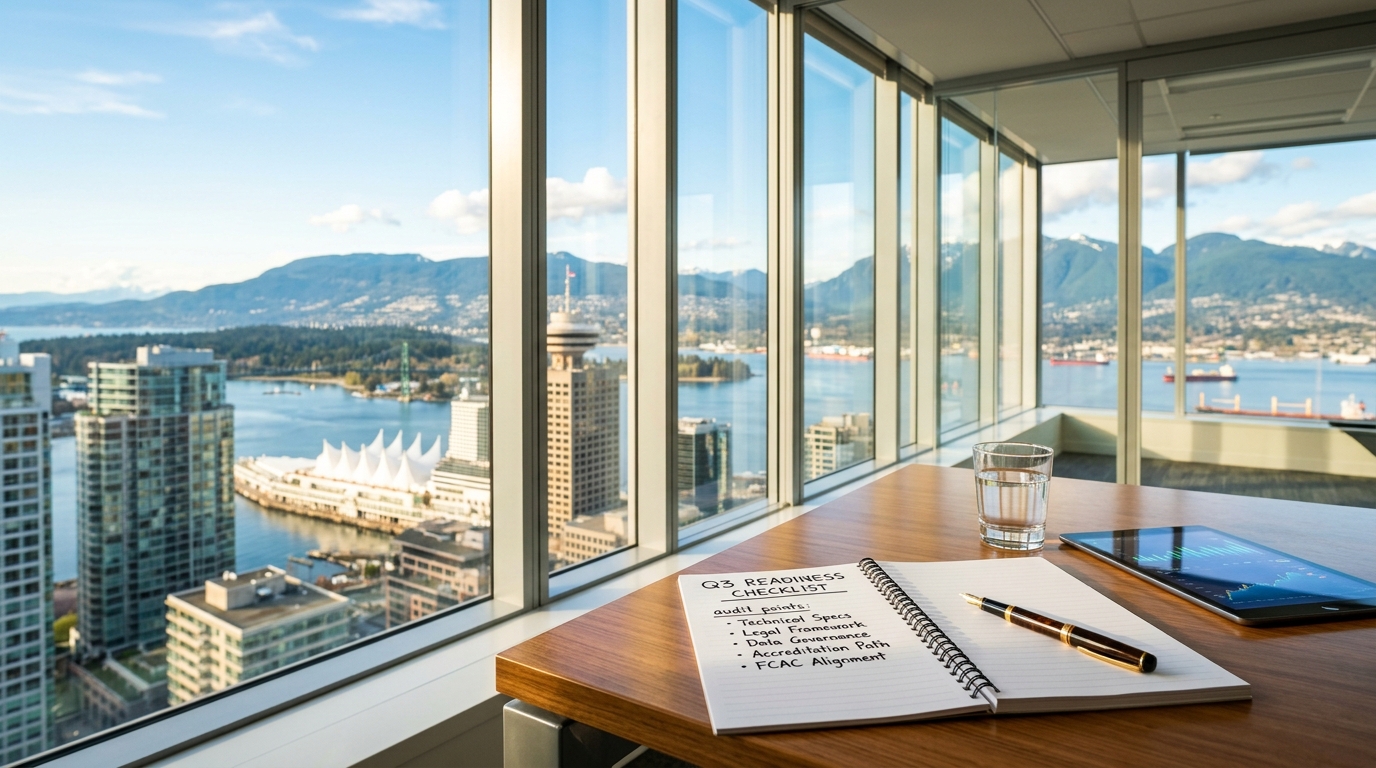
With the Financial Consumer Agency of Canada (FCAC) targeting Q3 2026 for the publication of accreditation criteria under the Consumer-Driven Banking Act, Metro Vancouver’s fintech founders are entering a 90-day pre-exam study window. While the exact release date remains unconfirmed, the syllabus—encompassing technical standards, legal obligations, and data governance—is largely knowable. Firms that use this quarter to audit their operations will be positioned to move quickly once the criteria are released.
Once-in-a-generation market access events reward preparation that, in hindsight, appears to have happened too early.
Why the timeline is real
The Consumer-Driven Banking Act received Royal Assent as part of the 2024 federal budget implementation bill, and the FCAC is currently building the accreditation regime. The agency’s public implementation communications point to Q3 2026 for the release of criteria. This provides a narrow runway for a compliance buildout that touches engineering, legal, and operations simultaneously.
The three-track audit
Industry observers have identified three parallel workstreams that every accreditation candidate should prioritize.
Track 1: Technical infrastructure. The open banking framework will require API connectivity standards aligned with the Financial Data Exchange (FDX) framework, as identified in federal policy statements. Firms must audit whether their current data-sharing architecture supports secure, consent-based flows at the required volume and latency. API remediation at small-to-mid-size fintechs typically requires eight to sixteen weeks once scoping is complete.
Track 2: Legal and regulatory readiness. Accreditation will impose new obligations regarding liability allocation, consumer consent, and incident reporting. Counsel recommend a gap analysis against the Department of Finance’s advisory committee recommendations, which serve as the closest proxy for formal requirements. This analysis often reveals material issues requiring board-level decisions before an application can be submitted.
Track 3: Data governance. This is where the accreditation bar is likely to be highest. Consumer-driven banking is fundamentally a consent and data-rights regime. Firms must demonstrate that their data governance frameworks—covering access, consent conditions, and audit trails—meet rigorous new standards. Building this framework requires engineering, product, and compliance teams to collaborate on documentation that many firms have yet to formalize.
The SME market context
The strategic stakes are significant. Canada’s SME banking market is a large, historically underserved segment. First-mover accreditation allows firms to offer data-sharing integrations to SME clients before competitors. In a market where switching costs are high, early accreditation provides a durable structural advantage.
What BC’s fintech community is doing
Industry sentiment suggests a mixed picture regarding readiness. Larger, better-capitalized Vancouver fintechs—particularly those with existing API infrastructure for international integrations—are well-positioned on the technical track. The gap is most acute among earlier-stage firms where compliance and legal functions remain founder-led and bandwidth is constrained.
For these firms, the 90-day window is demanding, but manageable if the audit begins immediately.
What to watch
- The FCAC criteria release: Any Q3 date, including preliminary consultation drafts, will reset the clock.
- Financial Data Exchange (FDX) specifications: These will define the API requirements for accreditation.
- Potential for phased accreditation: Any signal from the FCAC regarding a tiered approach would significantly alter the strategy for smaller fintechs.
- Readiness programming: Industry associations are expected to launch criteria-specific workshops once the FCAC documentation is public.




