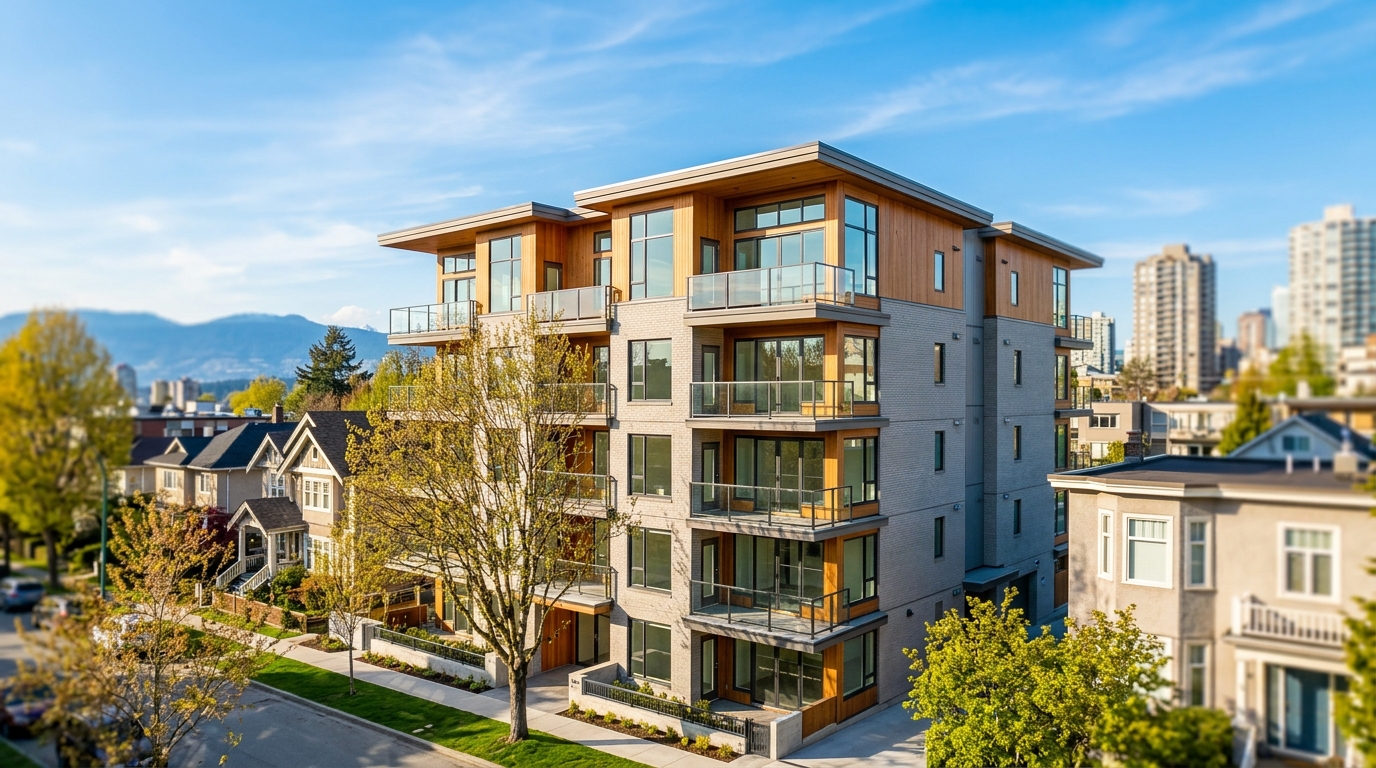
Picture a six-storey, 42-unit rental building on a corner lot in East Vancouver—exactly the kind of project that fills in a missing-middle neighbourhood without overwhelming it. A year ago, that project had a credible path to CMHC's Apartment Construction Loan Program (ACLP). Today, according to construction lenders and developers active in Metro Vancouver's rental market, that path has narrowed significantly. For many sub-60-unit projects, it has effectively closed.
The ACLP was designed to unlock this specific type of supply. CMHC has disbursed more than $2 billion through the program in British Columbia since its inception, making it the primary source of low-cost construction financing for purpose-built rental in the province. However, a structural tightening of underwriting criteria that took effect in Q1 2026—including revised debt-service coverage ratio (DSCR) thresholds—is concentrating capital among large institutional builders, leaving smaller operators to seek alternatives.
The mechanism is straightforward. CMHC's revised DSCR requirements demand that a project's net operating income cover its debt obligations by a margin that smaller buildings, with higher per-unit construction costs and thinner rent rolls, increasingly cannot meet at current market rents. A 120-unit tower spreads fixed costs across enough units to clear the bar; a 42-unit walk-up, facing the same land costs and trades labour rates, often cannot.
One Vancouver-based mortgage broker specialising in construction lending has noted publicly that raising the DSCR floor effectively sets a minimum project size for financial viability. Industry participants active in the Metro Vancouver development community estimate this effective minimum at roughly 60 units under the current framework, though this threshold is not an explicit policy change in CMHC's published guidelines.
The stakes are significant. Development industry data indicates that projects below 60 units have historically represented approximately 40 per cent of Metro Vancouver's purpose-built rental pipeline by project count—a disproportionate share of the missing-middle stock that bridges the gap between single-family neighbourhoods and large-scale towers. These buildings are structurally the most difficult to finance without low-cost federal capital.
CMHC forecasts approximately 6,500 purpose-built rental completions across Metro Vancouver in 2026. While this figure appears robust, the pipeline composition is shifting toward larger projects. Fewer small buildings in the financing queue today means fewer small buildings delivering keys in 2028 and 2029.
The revised underwriting reflects a focus on the program's long-term financial integrity. Tightening DSCR thresholds in an environment where construction costs remain elevated and interest rates have not fully normalised is a risk-management decision. The challenge lies in the unintended consequence of excluding smaller, contextually appropriate developments.
Strategic alternatives for smaller developers
For operators caught on the wrong side of the new threshold, alternatives remain available, though at a higher cost. Private lenders such as Trez Capital and Antrim Investments remain active in the sub-60-unit space, though at rates that can run 150 to 250 basis points above CMHC's preferred terms—a meaningful drag on thin pro formas.
BC Housing's Rental Housing Fund offers another avenue for projects with an affordable component, though the pipeline is competitive and approval timelines are longer. The province's BC Builds program, which pairs public land with private development for middle-income rental, is a viable option for developers willing to work with a public-sector partner.
Creative deal structures are also gaining traction. Some developers are exploring phased development agreements that aggregate smaller sites into a single financing envelope, manufacturing the scale CMHC now requires without building a single large tower. Others are partnering with non-profit housing societies, whose access to dedicated affordable housing financing streams can unlock capital unavailable to private developers acting alone.
The Urban Development Institute's Pacific Region chapter has flagged the underwriting shift as a priority advocacy issue for 2026. Sustained industry pressure, combined with a provincial government focused on rental supply, could prompt CMHC to revisit thresholds for high-demand urban markets. That process, however, will take time.
The bottom line
The ACLP remains the most powerful tool in Metro Vancouver's rental financing toolkit, but its revised terms are better suited to institutional builders than to the small and mid-market developers who have historically delivered the city's most contextually appropriate rental housing. If you are operating in the sub-60-unit space, the window for CMHC financing has narrowed. The operators who move fastest to map alternative capital stacks—private lending, provincial programs, non-profit partnerships, or creative site aggregation—will be the ones who keep their pipelines alive. Watch for CMHC's next program review, expected in Q3 2026, for signals of a potential recalibration.



