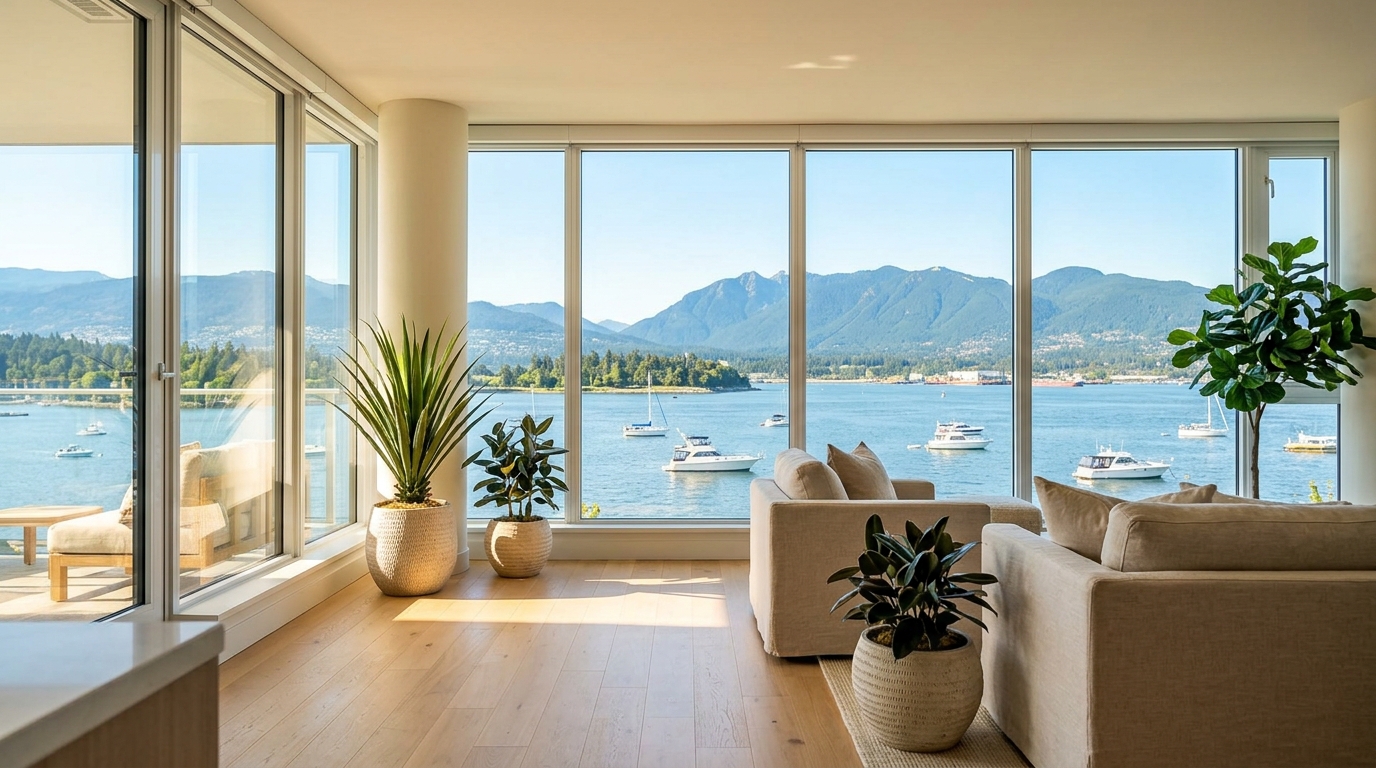
Walk through Coal Harbour on a weekday morning and the stillness tells a story. Towers conceived when global capital flowed freely into Vancouver presales now sit with unsold inventory that developers are managing with caution. The foreign buyer ban, extended to January 1, 2027, has reshaped the calculus of luxury development in Metro Vancouver. However, the legislation includes a periodic regulatory review mechanism, and the window for reassessment is coming into focus.
The Prohibition on the Purchase of Residential Property by Non-Canadians Act requires federal housing officials to assess the policy's effectiveness as new housing supply comes online. While specific officials have not publicly committed to a timeline, the government has acknowledged the need to monitor market conditions—a signal that Vancouver’s development community is watching closely. This is the legislation functioning as designed: creating a structured moment to determine if the original policy rationale remains relevant.
Greater Vancouver REALTORS (GVR) data from Q1 2026 shows detached home inventory reaching 18-month highs, sitting above 10-year seasonal averages in several West Side districts. This buildup reflects, in part, the absence of a buyer class that once absorbed a meaningful share of the $3M-plus tier. Pre-ban, CMHC data placed non-resident ownership at approximately 3.1% of Metro Vancouver's total housing stock—a figure that understates the segment's outsized role in the luxury and presale markets, where international buyers historically concentrated their activity.
Who Unlocks Capital First
Not all submarkets would benefit equally from a policy reversal. Coal Harbour, West Vancouver's waterfront corridor, and the Westside—Shaughnessy, Kerrisdale, Point Grey—represent the three zones where stalled international demand is most directly priced into current inventory. These are neighbourhoods where the development pipeline was modelled on offshore presale absorption, and where the repricing impact of a policy shift would be most measurable.
The luxury tier—properties above $3M—is where the arithmetic is most sensitive. With days-on-market stretching in the luxury detached segment and developers carrying longer presale periods than their pro formas anticipated, even a partial reopening of the foreign buyer market could compress inventory and reset price expectations. Developers currently structuring projects with domestic buyer assumptions would find a deeper pool of qualified purchasers for their highest-margin units.
What Developers Are Doing Now
Developers with projects in the luxury pipeline are structuring presale programs with optionality—pricing and suite configurations that serve domestic buyers today but can accommodate international demand if restrictions ease. Some are maintaining relationships with offshore marketing channels that went dormant in 2023.
Urban Development Institute Pacific data on the regional pre-sale pipeline reflects the degree to which the luxury segment has been treading water. Projects that would have launched in 2022 have been held at earlier stages, their business cases contingent on a buyer mix that the ban disrupted. A policy reversal would likely accelerate launch decisions on projects currently waiting for demand-side conditions to improve.
The CRA's Underused Housing Tax filings offer a proxy for understanding where non-resident capital is currently parked. Properties subject to the UHT—those owned by non-Canadian, non-permanent-resident holders—represent a pool of assets whose owners have been paying a carrying cost to maintain their positions. A policy shift could add transaction velocity to the luxury market from both the buy and sell sides.
The Affordability Counterweight
The legislation emerged from concerns that offshore capital contributed to affordability pressures in markets where local incomes were stretched. The BCFSA property transfer data documented the geographic concentration of non-resident purchasing activity, noting it was not evenly distributed across the market.
The policy debate that a formal review would trigger is not simply about unlocking developer upside. It is about whether the mechanism causing harm—concentrated offshore purchasing in entry-level and mid-market segments—can be addressed without restricting the luxury and presale segments where international demand plays a different role. That is a genuine policy question, and the outcome is not predetermined.
The Bottom Line
Canada's foreign buyer ban was a temporary measure with a periodic regulatory review clause. With the current extension running to January 2027, the policy inflection point is real. For luxury developers, the priority is structuring projects and presale pipelines so that international demand can be absorbed if the window reopens. Watch the federal housing supply benchmarks closely: those numbers will indicate how close the gate is to opening.



