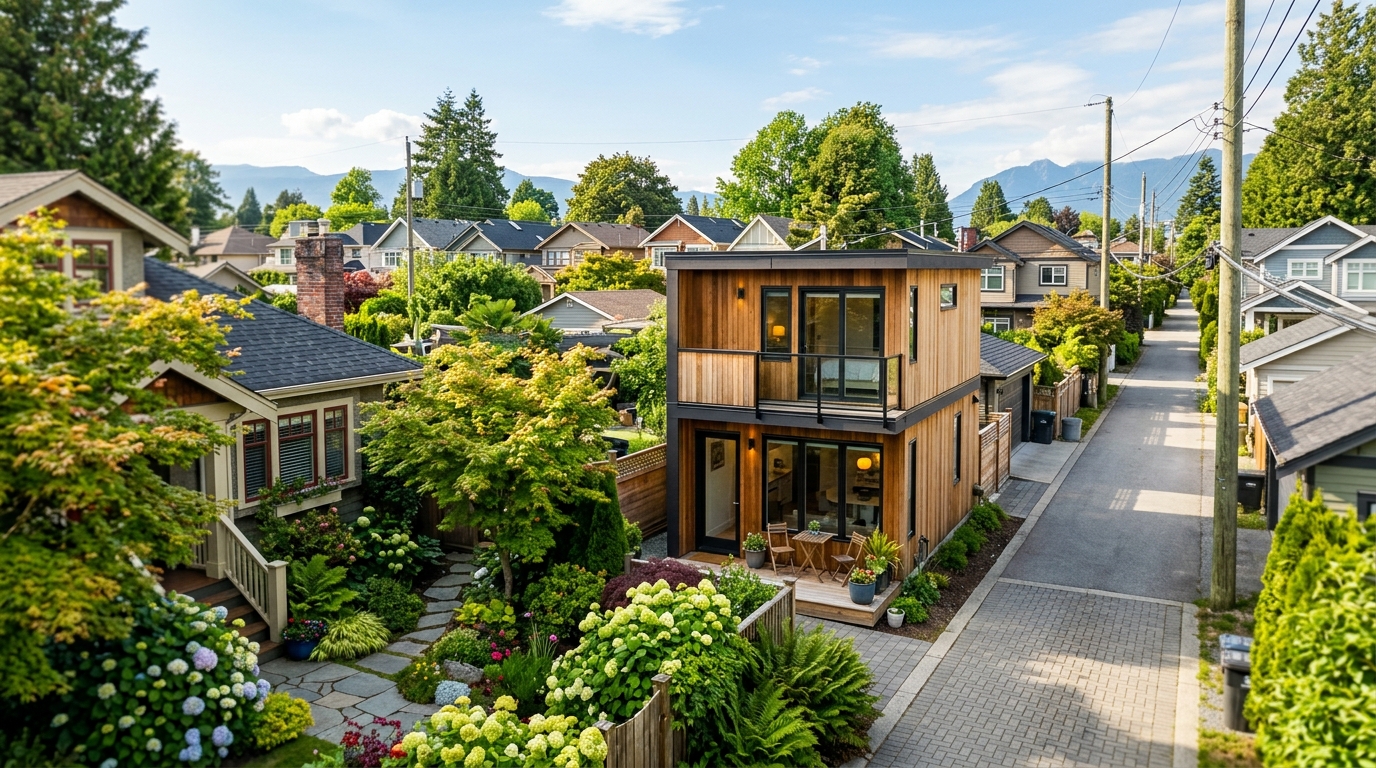
Walk the back alleys of East Vancouver on a weekday morning and the landscape is shifting. The structures rising behind century-old homes are no longer hobby projects or in-law suites. They are purpose-built, architect-designed units, often held by the same numbered company that owns similar properties across the neighbourhood.
Vancouver's laneway and garden suite market is undergoing a structural transformation. What began as a homeowner-driven densification tool is evolving into a micro-rental asset class being assembled by a new generation of small-scale institutional investors. The policy infrastructure arrived in two waves. BC's Bill 44, passed in late 2023, mandated small-scale multi-unit housing on most single-family lots, removing the discretionary approval process that had long throttled supply. Then, Vancouver's 2025 multiplex and infill zoning expansion permitted larger footprints and additional units. It is important to distinguish between traditional laneway suites, which are typically non-stratified, and multiplex units, which can be separately titled under the 2025 rules.
The City of Vancouver's Development and Building Services division is expected to release Q1 2026 permit data imminently. These figures are anticipated to reflect record application volumes, confirming that the laneway suite is no longer a niche product.
The Financing Gap
The financing ecosystem has not kept pace with this policy shift. Traditional lenders treat laneway suites inconsistently; some include rental income in a borrower's qualifying income, while others do not. Furthermore, CMHC's standard insured mortgage programs, designed for conventional rental buildings or owner-occupied homes, do not map cleanly onto a portfolio of detached suites scattered across multiple properties.
CMHC's most recent Metro Vancouver Rental Market Report shows purpose-built rental vacancy rates near historic lows, supporting the investment thesis. However, the valuation of these micro-rental portfolios remains challenging. BC Assessment's methodology has historically folded laneway suite value into the overall property assessment rather than treating it as a standalone income-producing asset, creating a disconnect for investors seeking to demonstrate portfolio value.
Insurance and Management
Insurance remains a hurdle. Standard homeowner policies are often ill-suited for properties where the owner lives elsewhere and both the principal dwelling and the laneway suite are tenanted. Commercial landlord policies exist, but underwriters are still calibrating risk models for detached micro-units managed as part of a larger portfolio.
The Urban Development Institute of BC has flagged this financing and valuation gap as a policy priority, arguing that financial infrastructure must evolve to support the province's mandated supply.
Strategic Investment
Successful investors in this space are working with mortgage brokers who specialize in portfolio-level underwriting through credit unions and alternative lenders. They are commissioning independent appraisals based on income capitalization rather than relying solely on BC Assessment values. Furthermore, they prioritize lot selection near SkyTrain and bus rapid transit corridors, where rental demand is structurally stronger.
The neighbourhood calculus is vital. A laneway suite in Grandview-Woodland operates in a different market than one in South Vancouver with limited transit access. Investors who underwrite at the block level are finding real yield.
The Bottom Line
Vancouver's laneway suite is graduating from a homeowner amenity to a commercial asset class. The current lag in financing and valuation infrastructure represents a window of opportunity. Those who master portfolio-level financing and income-based appraisals will hold a structural advantage as the market matures.



