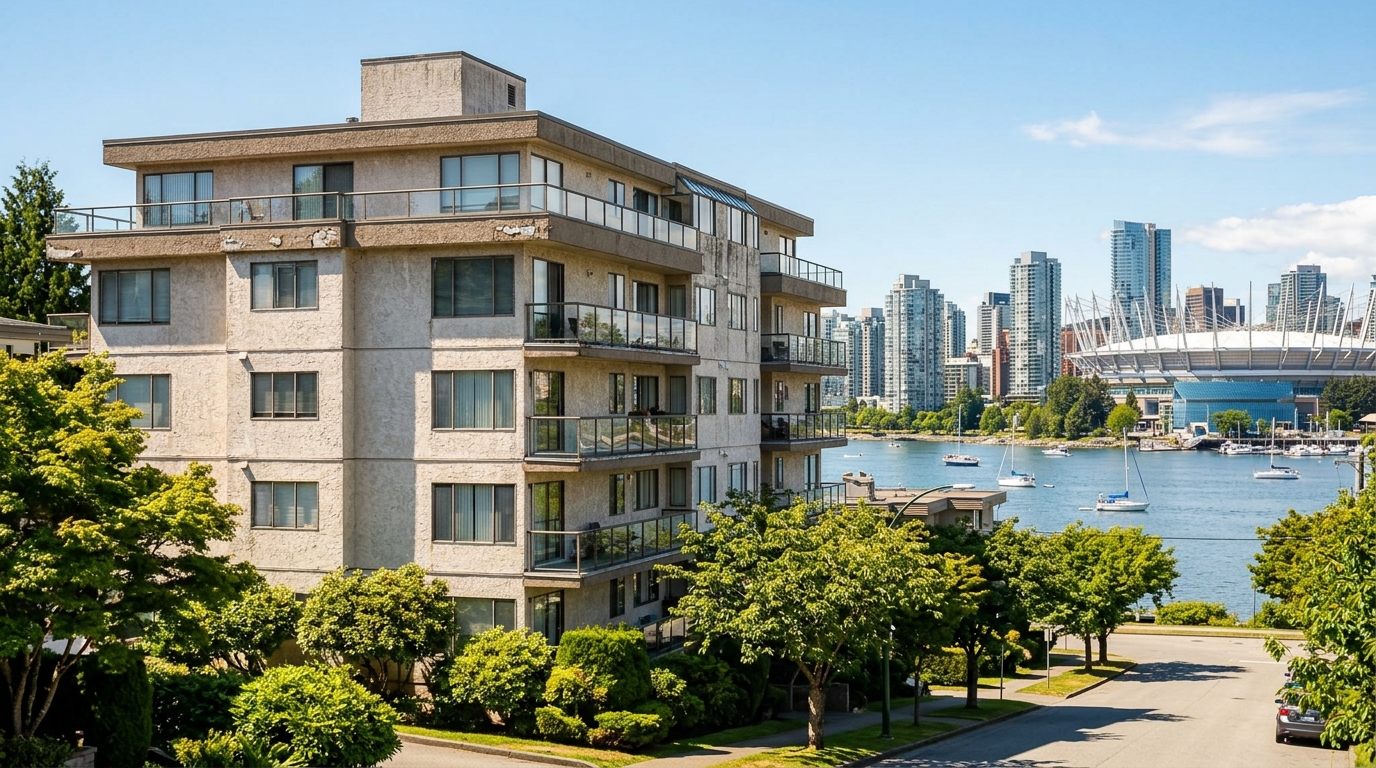
Picture a 1987 concrete tower in Burnaby’s Brentwood neighbourhood: 120 units, a reserve fund that covers the boiler and the lobby carpet, and a letter from the City advising that its electrical panels must be brought up to current code within three years. The strata council calls three banks. Two do not return the call. The third explains that they do not lend to strata corporations. The council turns to its owners—many of them landlords, some of them retirees on fixed incomes—and levies an $18,000 special assessment per unit. Two owners immediately list their suites for sale.
This scenario is playing out across more than 10,000 strata corporations in Metro Vancouver, the majority of which were constructed before 2000. The upgrades being demanded—seismic reinforcement, panel replacements, envelope repairs, and energy retrofits tied to municipal carbon emission limits and the CleanBC Roadmap—are not optional. The financing to pay for them, however, remains out of reach for most strata councils.
The result is a retrofit finance gap: a chasm between the capital strata corporations need and the capital the market is currently willing to provide. Estimates of the total cost of deferred maintenance and mandatory upgrades across Metro Vancouver’s pre-2000 strata stock run into the billions of dollars. The Canada Mortgage and Housing Corporation has flagged strata financing as an underserved segment of the Canadian lending market, noting that the legal and governance complexity of strata ownership creates friction that conventional lenders are reluctant to absorb.
Why Banks Say No
Understanding the finance gap requires understanding why institutional lenders avoid stratas. The barriers are structural.
Under the BC Strata Property Act, a strata corporation is a legal entity without land title in its own name, as individual unit owners hold title. The primary legal hurdle is that a strata corporation cannot use common property as collateral. If a loan defaults, foreclosing on common property is legally complex and practically uncharted territory in BC courts. Furthermore, many older stratas are chronically underfunded relative to their depreciation reports. Lenders who perform due diligence often find that reserve funds cover less than half of projected 30-year capital expenditures—a red flag that triggers an automatic decline at most credit committees.
Governance risk is the third factor. A strata council that approves a loan today can be replaced at the next annual general meeting by a council that may not share the same appetite for debt.
Who Is Actually Lending?
The institutional vacuum has created room for credit unions and mission-driven lenders to step in.
Vancity Credit Union’s Green Building program is among the most active lenders in the strata retrofit space in BC, offering financing for energy efficiency upgrades, including heat pump conversions, envelope improvements, and solar installations. The program bridges the gap between a strata’s reserve fund and the full project cost, with repayment structured to align with the energy savings the upgrade generates.
Other BC credit unions have begun developing similar products, partly in response to guidance from the BC Financial Services Authority encouraging credit unions to develop lending frameworks suited to strata governance structures.
The Special Assessment Burden
When financing falls through, strata councils rely on special assessments. The Condominium Home Owners Association of BC (CHOA) has documented a significant rise in the size and frequency of these assessments over the past five years as deferred maintenance bills coincide with new code requirements.
The impact on resale values is measurable. A unit in a building with a pending special assessment typically trades at a discount. Buyers and realtors have become more sophisticated in reading depreciation reports, and a strata with a chronically underfunded reserve is increasingly treated as a distressed asset.
The Fintech and Securitization Opportunity
The most intriguing solutions involve rethinking strata retrofit financing at a structural level. In other jurisdictions, property-assessed clean energy (PACE) financing allows building owners to repay retrofit costs through a levy attached to the property title. While BC does not yet have a PACE framework, advocates including some municipal governments have been pushing for enabling legislation.
Fintech firms are exploring securitization models that would pool retrofit loans across multiple strata corporations—diversifying the governance and default risk—and sell the resulting securities to institutional investors. While no such product has launched at scale in Canada, the structural logic is sound and market appetite among ESG investors is present.
The Bottom Line
For strata owners and councils, the most actionable steps are to update depreciation reports, benchmark reserve funds against projected 30-year capital needs, and engage property managers with retrofit financing experience. Vancity’s Green Building program and similar credit union products represent capital available now.
For lenders, the opportunity is clear. The strata retrofit gap is a multi-billion-dollar market that institutional lenders have largely declined to serve. The legal and governance complexity is solvable, and first movers who build products suited to strata governance will have a structural advantage as buildings age and code deadlines approach.



