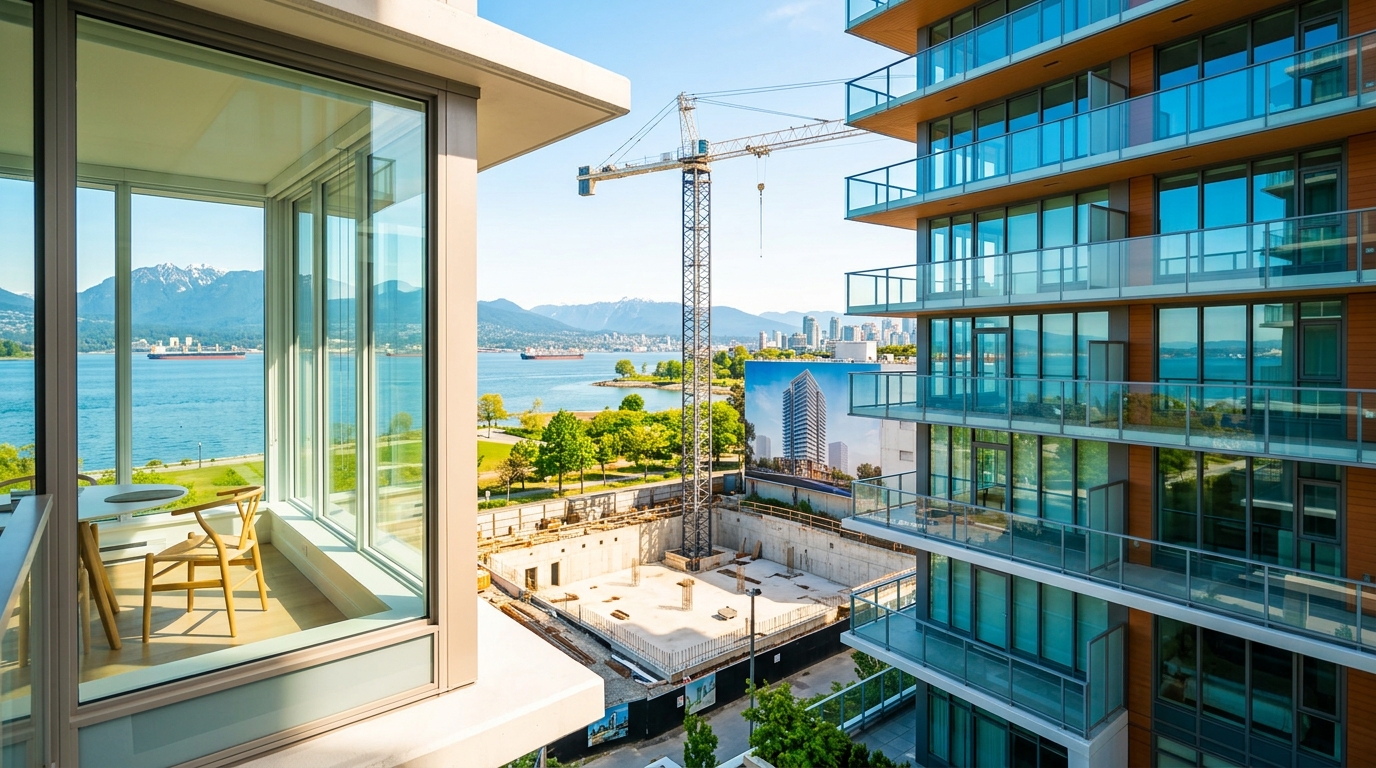
Stand at the corner of any arterial corridor in East Vancouver or Burnaby’s Brentwood neighbourhood and you will see the same thing: rezoning signs, architectural renderings on hoarding boards, and—increasingly—silence where cranes should be. The projects are approved. The demand is undeniable. What is missing is the capital to build.
Metro Vancouver’s purpose-built rental sector faces a financing crisis rooted in the gap between what lenders offer and what rental economics can support. Metro Vancouver’s rental vacancy rate sat at approximately 0.9 per cent in CMHC’s most recent Rental Market Report. In a functioning market, this should be sufficient signal to unlock capital at scale. Instead, a growing cohort of projects with municipal approvals are sitting in pre-construction limbo, unable to secure financing at terms that make the numbers work.
This is a structural financing gap that is quietly strangling Metro Vancouver’s housing supply pipeline, limiting the ability of employers across the region to recruit and retain the workers they need.
The Gap, Quantified
The core problem is the spread between conventional construction financing and the terms available through CMHC’s MLI Select program, which offers lower-rate insured financing for projects meeting specific affordability, accessibility, and energy efficiency criteria. While a lifeline for those that qualify, the program’s capacity is not unlimited, and qualification is neither automatic nor fast.
For projects unable to access MLI Select, conventional construction financing is currently quoted at rates that render many projects unviable against rental revenues capped by BC’s rent increase guidelines. Lenders have tightened loan-to-cost ratios and are stress-testing projects at rates that leave insufficient margin for developers who acquired land at 2021 or 2022 valuations.
The Urban Development Institute of BC has tracked a meaningful share of purpose-built rental units in the Metro Vancouver pre-construction pipeline that have not yet secured construction financing. Industry observers describe the volume of stalled approvals as the largest since the 2018 interest rate cycle.
BC Housing’s construction financing programs have partially filled the gap for projects with deeper affordability commitments, but these are structured for the lower end of the rent spectrum, not the mid-market towers that comprise the bulk of the stalled pipeline.
What Lenders Are Seeing
Mortgage investment corporations and development finance specialists report that rental project underwriting has become substantially more conservative since mid-2024. The issue is not a total cessation of lending, but that current terms no longer pencil for a significant subset of projects.
A tower’s debt serviceability is constrained by its net operating income, which is limited by market rents and operating costs. With construction costs—including trades labour and materials—remaining near 2022–2023 peaks, and lenders applying conservative vacancy assumptions and high stress-test rates, the viability gap can reach tens of millions of dollars on a mid-sized tower.
Data tracked by the BC Financial Services Authority on MIC lending activity reflects a shift toward shorter-term bridge positions and away from full construction loan commitments, signalling that even alternative lenders are hedging exposure to this asset class.
Commercial real estate advisors tracking Metro Vancouver’s rental development pipeline note that projects in the 100-to-200 unit range—the scale expected to deliver the most new supply—are the most acutely affected. They are too large for community-focused programs but too small to absorb the overhead of complex structured financing.
The Employer Consequence
For Metro Vancouver’s business community, the stalled rental pipeline is a direct constraint on hiring. The region’s labour force housing shortage is a recurring theme in economic development conversations across sectors, from healthcare to technology.
The City of Vancouver’s development pipeline data shows a substantial volume of rezoned and approved rental capacity that has not yet broken ground. If this backlog continues to stall, the gap between housing supply commitments and actual delivery will widen through the remainder of the decade.
Employers in sectors dependent on attracting talent from outside Metro Vancouver are beginning to treat housing availability as a recruitment variable on par with compensation. Some larger employers are exploring direct partnerships with rental developers, including subordinated equity contributions, to help bridge financing gaps near major employment nodes.
Where Deals Are Still Getting Done
Not all rental development has stalled. Projects with strong MLI Select qualification continue to advance, benefiting from lower debt service costs and longer amortisation periods. Institutional developers with balance-sheet capacity to self-fund equity gaps are also moving forward, as are projects in municipalities that have layered in additional density or development cost charge relief.
CMHC has approved a significant volume of MLI Select applications in Metro Vancouver, but the program’s underwriting timeline means it cannot absorb the full pipeline. Provincial policy levers remain available, and municipal contributions—through density bonusing and reduced development cost charges—are being revisited by several local governments to improve project feasibility.
The Bottom Line
Metro Vancouver’s rental supply problem is a financing architecture issue. The gap between what rental economics can support and what lenders require has stalled a meaningful share of the approved pipeline. Every month this persists, the labour force housing deficit compounds.
For investors, the signal is that rental development risk is being mispriced at the project level. For policymakers, the path forward involves expanding MLI Select capacity, accelerating underwriting timelines, and layering in provincial construction financing for mid-market projects. The demand is there; the approvals are there. The missing piece is financing that reflects the long-term value of rental housing.
Watch for: CMHC’s next comprehensive housing update, which will provide a fresh read on vacancy and rental completions across Metro Vancouver. The Urban Development Institute BC’s annual member survey, typically released in late summer, is expected to quantify the scale of the stalled pipeline.



